


News & Exhibitions
Latest Factory Updates, Industry Trends & Global Exhibition Information
Global Wood Price Decline Cuts Woodworking Equipment Maintenance Costs, Spare Parts Lead Time Drops to 12 Days
Effective September 13, 2026, a notable decline in global timber prices—driven by corrections in North American softwood and Russian birch imports—is generating measurable cost benefits for the woodworking industry. Analysis suggests this shift is directly reducing procurement expenses for key spare parts used in mainstream woodworking machinery, including HOMAG and Biesse domestic alternatives. With average cost reductions of 11% to 18% on items such as tooling, guide rails, and servo motors, and a reported increase in overseas warehouse stock levels to 89%, end-users now face shorter downtime risks and a compressed average lead time of 12 working days. This development warrants attention from operators managing production continuity, procurement budgets, and supply chain reliability in the woodworking sector.
Price Correction in Raw Materials Triggers Downstream Savings
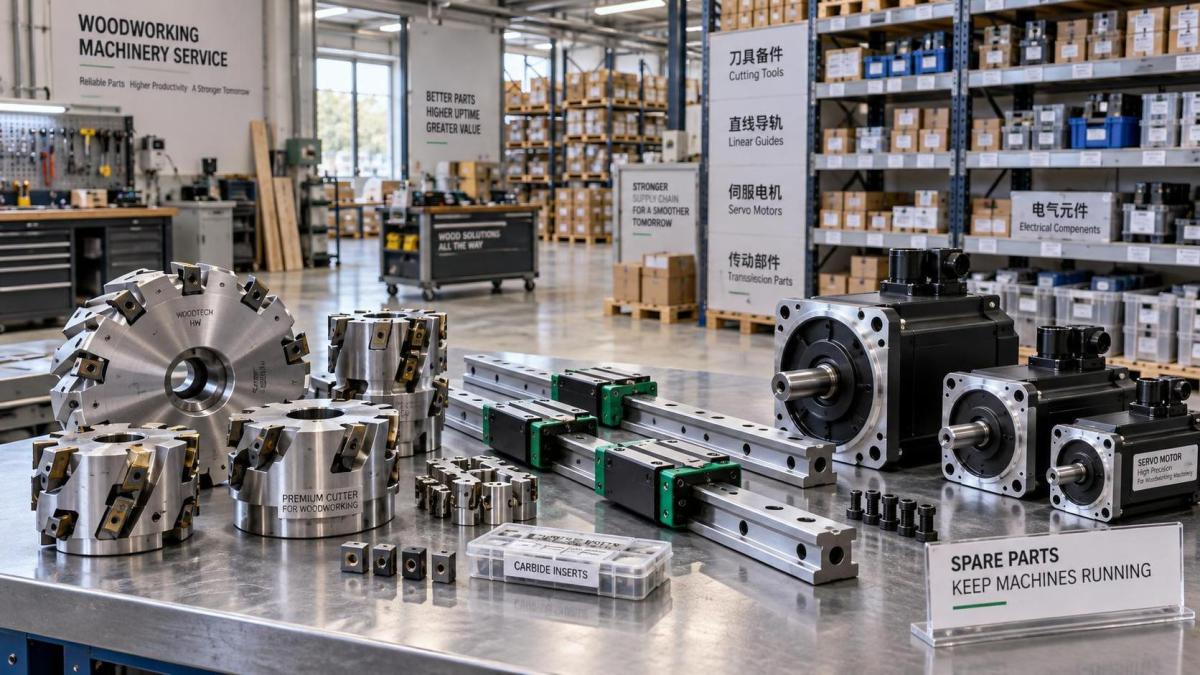
According to the provided information, from September 2026, the cost of commonly used spare parts for mainstream woodworking machinery declined by 11% to 18%. This reduction is linked to the price adjustment of imported North American softwood and Russian birch. Industry reports indicate that a major Chinese service provider has increased its overseas warehouse stocking rate to 89%, enabling a significantly reduced lead time of 12 working days for deliveries. Confirmed data focuses on the direct impact on procurement expenditures and delivery timelines for specific component categories like cutters, guide rails, and servo motors.
Impacts Across the Value Chain: From Procurement to End-User Operations
Maintenance Service Providers and Aftermarket Parts Suppliers
Companies that specialize in maintenance, repair, and operations (MRO) for woodworking equipment may see improved profit margins or greater pricing flexibility. The combination of lower purchase costs and faster order fulfillment suggests reduced capital tied up in inventory and enhanced ability to meet urgent service requests, particularly for end-users seeking to minimize production interruptions.
End-User Manufacturers and Production Facilities
Facilities operating HOMAG, Biesse, or equivalent domestic machinery could experience lower overall maintenance expenditures. The shortened lead time—down to an average of 12 working days—implies that unscheduled downtime events may be resolved more swiftly, potentially increasing overall equipment effectiveness (OEE). This change influences budgeting for spare parts and may shift purchasing patterns toward higher inventory turnover.
Trading and Procurement Teams
Procurement professionals should note that the cost benefits and lead time improvements appear to be concentrated among service providers with significant overseas warehouse infrastructure. This could influence vendor selection criteria, with emphasis now placed on logistics capabilities and stock availability rather than solely on unit price. Trade flows for parts might become more regionalized as local stock levels rise.
Strategic Considerations for Industry Participants
Review Existing Supplier Agreements and Stocking Policies
Given the shift toward higher overseas warehouse stock rates (89%), companies should evaluate whether current service level agreements reflect the new lead time reality. Contract terms that previously accounted for longer shipping delays may need to be renegotiated to capture logistics efficiencies and cost savings.
Assess Procurement Volumes and Inventory Rebalancing
The 11%–18% price reduction for components like servo motors and guide rails may present an opportunity to optimize order quantities. However, careful analysis is required to determine whether the price drop is sustainable or a short-term market reaction. Companies should adjust inventory levels accordingly to avoid overstocking if prices rise again.
Monitor Supply Chain Stability and Alternative Sourcing
While the average lead time has compressed to 12 days, this improvement is linked to one major service provider. Industry participants should verify whether similar performance is achievable from other vendors. Diversifying sources—perhaps by considering domestic alternatives to imported brands—could mitigate risks if supply conditions change. Compliance with any applicable trade rules or import regulations should also be reviewed.
Editorial Assessment: More a Confirmed Market Shift Than a Policy Signal
Based on the available information, this development reflects an executed change in market conditions—lower raw material costs and improved logistics performance—rather than a regulatory or policy adjustment. The data points on price decreases and lead time compression appear to represent results that have already been realized in transactions. However, it would be premature to assume these benefits are universal across all markets or will persist indefinitely. Companies should treat this as a near-term operational gain while remaining attentive to raw material price trends and potential supply chain disruptions. The absence of formal rule changes or certification updates means no compliance adjustments are required, but procurement and maintenance teams should incorporate these conditions into upcoming budgeting cycles.
Outlook: Practical Implications for Operational Planning
The combination of lower spare parts costs and faster delivery times represents a tangible improvement for woodworking equipment maintainers. While this shift does not alter regulatory or certification landscapes, it does provide immediate operational advantages that can enhance cash flow and equipment uptime. The most prudent course for industry players is to validate these cost and lead time metrics with their specific service providers, adjust inventory strategies accordingly, and monitor the timber market for signs of reversal. This information is best understood as a confirmed market adjustment that offers measurable, though potentially temporary, benefits for end-users.
Basis of This Report
This article is generated solely from the user-provided input: the news title, event date (September 13, 2026), and event summary. No specific official source links (e.g., government announcements, regulatory filings, or trade association publications) were included in the input. Industry participants are advised to verify the cited cost reductions and lead times directly with their suppliers and to continue monitoring raw material price indices and logistics reports for further confirmation of these trends.
Send Your Inquiry
We welcome your cooperation and we will develop with you.